Which KYC documents does a UAE business bank account need?
Prepare a UAE corporate bank account KYC file covering the entity, ownership, signatories, business model, source of funds and expected transactions.
A useful UAE corporate-account file answers six questions: which entity is applying, who ultimately owns and controls it, who may act for it, what the business does, where its capital came from and what transactions the bank should expect. There is no universal closed list: the bank applies risk-based due diligence and may request more evidence.
The current CBUAE Customer Due Diligence framework, effective from 7 November 2025, covers identity and beneficial ownership, purpose, source of funds/wealth, expected activity, ongoing monitoring and customer rejection or exit.
Build the file around compliance questions
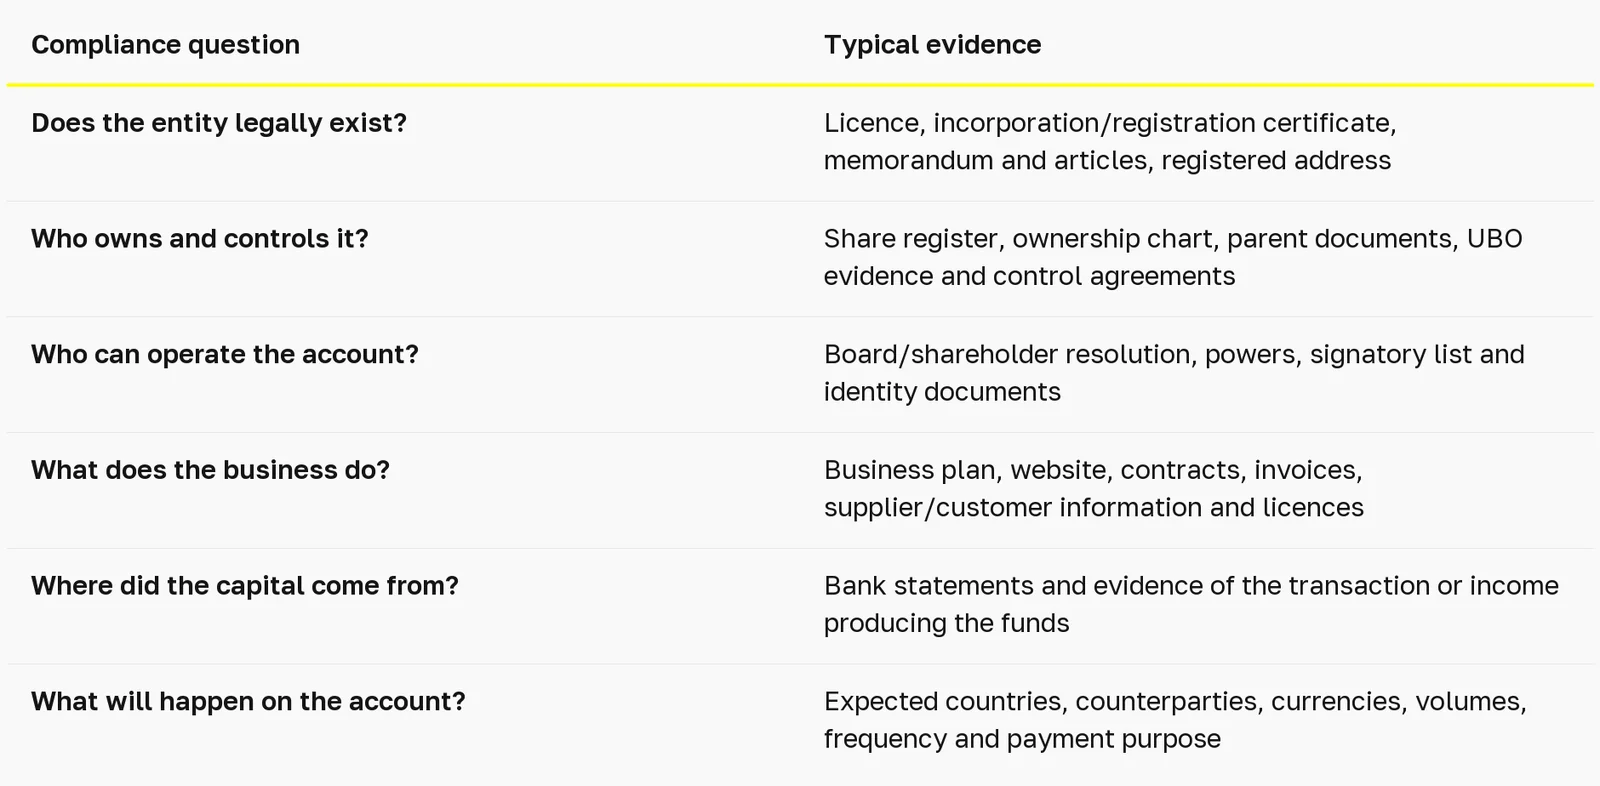
The bank decides sufficiency. An ADIB business-banking checklist, for example, expressly reserves the right to request additional documents or amend its requirements.
Entity and constitutional documents
Prepare the current trade licence and formation record, constitutional documents, registered office evidence and any amendments. The company name, legal form, address, activities, managers and authorised persons should be consistent across the pack.
Foreign corporate shareholders usually require their own registry and constitutional evidence. Under the CBUAE legal-person verification rules, foreign entities without UAE presence may be verified through certified incorporation documents, proof of principal place of business and identification of controlling individuals.
Ownership and control chain
A chart should trace every intermediate entity to the relevant natural persons and explain voting, appointment, nominee or other control rights. The current CBUAE guidance for legal persons requires look-through across ownership/control layers and considers common ownership in aggregate.
Do not submit a decorative chart that cannot be reconciled with registers, shareholder agreements and IDs. Date the chart and identify the evidence for each link.
Signatories and authority
For directors, authorised signatories and other account users, prepare identity/address documents applicable to their status and the corporate instrument authorising them. The bank may need to verify both the person and the scope of authority, including remote users.
Business-model evidence
A licence proves that an entity exists; it does not prove that the proposed flows make commercial sense. Add:
- a concise company profile and reason for operating in the UAE;
- product/service descriptions and customer journey;
- signed or draft customer/supplier contracts;
- invoices, purchase orders or pipeline evidence where available;
- website/domain and group-company explanation;
- countries, counterparties and delivery model;
- relevant sector approvals and premises evidence.
For a new company, forward-looking evidence matters. Projections should be assumptions the business can explain, not artificial documents created to imitate trading history.
Source of funds is not source of wealth
The CBUAE rulebook distinguishes them: source of funds is the direct source of money used to fund or transact through the account; source of wealth explains what generated the person’s total net worth.
Evidence depends on the stated source and risk: bank/broker statements, salary or dividend records, financial statements, sale agreements, property records, inheritance or court documents may be relevant. A declaration should identify the route; it does not replace supporting evidence when verification is required.
Expected-activity sheet
Record the first twelve months by transaction type:
- incoming/outgoing purpose;
- customer or supplier category;
- countries and currencies;
- monthly count and range;
- largest expected transaction;
- payment channel;
- supporting contract or invoice;
- reason the flow matches the licence.
This is not a promise that every forecast will be exact. It gives the bank a baseline and makes inconsistencies visible before application.
Higher-risk or complex files
More evidence may be required for multilayer groups, high-risk countries, PEP exposure, cash-intensive models, virtual assets, commodities, dual-use goods, trusts/foundations or flows inconsistent with the declared profile. Do not conceal complexity. Explain it and provide the document chain.
Data-room index before submission
Use numbered folders for entity, ownership, people/authority, business, funds/wealth and expected activity. Record issuer, document date, expiry, certification/translation status and the question each document answers. Remove obsolete drafts and reconcile contradictions.
For application strategy and bank-facing preparation, use UAE corporate bank-account support. If an application has already failed, use the separate guide on diagnosing a bank-account rejection.
Frequently asked questions
Is a trade licence enough to open a UAE business account?
No. The bank also needs to understand ownership/control, authorised persons, purpose, source of funds and expected activity.
Must every shareholder provide documents?
Requirements depend on ownership, control and bank risk assessment. Expect evidence through the ownership chain and for relevant natural persons; do not rely only on a percentage shortcut.
Do non-resident owners need a UAE residence visa?
The document route depends on the bank and product. Non-resident status does not remove identity, address, ownership and source-of-funds checks.
How many months of statements are required?
There is no universal period. Follow the selected bank’s current checklist and the source being proved.
Does a complete checklist guarantee approval?
No. Banks make independent risk and commercial decisions and can request more evidence or decline.
Should documents be translated or certified?
That depends on issuer, language, bank and document type. Confirm the selected bank’s current acceptance requirements before submission.
Official CBUAE rules and institutional checklists checked 20 July 2026. The selected bank’s current requirements control the application. General information only.
Discuss
the Task
Speak to our team
Speak to our team. Tell us about your task –
we’ll help you with it in any jurisdiction.